After a major storm, most homeowners assume they’re covered. Then the adjuster arrives and says three words that change everything: “This is flooding.” Suddenly, a claim that seemed straightforward becomes a coverage dispute, and depending on what policies you carry, it could mean the difference between a full payout and paying out of pocket.
Storm damage and flood damage may look identical from inside your home, but they’re treated very differently by insurance companies. Knowing which is which, before a storm hits, could save you thousands of dollars and weeks of frustration.
At a Glance
- Standard homeowners insurance covers storm damage: wind, hail, lightning, and water that enters through storm-created openings.
- Flood damage (water rising from the ground) is NOT covered by homeowners’ insurance and requires a separate flood policy.
- Wind-driven rain that enters through a broken window or damaged roof is typically covered. Ground flooding is not.
- Hurricane claims are especially complex. Storm surge is flood damage, while wind damage is typically covered separately.
- Documentation matters: photograph all damage before cleanup and notify your insurer immediately.
What Counts as Storm Damage on a Homeowners Policy?
Homeowners’ insurance is built to cover sudden and accidental damage from weather events and some internal water losses that may cover water damage.
Storm damage typically includes:
- Wind damage: A tree limb crashes through your roof, a windstorm tears off shingles, or a gust breaks windows.
- Hail damage: Ice pellets dent your roof, siding, or HVAC equipment.
- Lightning strikes: A direct hit causes a fire or electrical damage.
- Wind-driven rain: Rain that enters your home through an opening the storm created a broken window, a torn-off roof section, a fallen tree is generally treated as storm damage.
Burst pipes are typically covered by homeowners insurance policies, and water damage from appliance failures is generally covered, unlike flood damage.
What Makes Wind-Driven Rain a Covered Loss?
The principle is causation. If wind physically created an opening and rain followed through that opening, most standard homeowners’ policies cover the resulting water damage as storm-related. This is the wind-driven rain insurance distinction that trips up a lot of homeowners.
If your roof was intact before the storm and is now missing shingles, with rain pooling in your living room as a result, that’s a storm claim. Your homeowners’ policy should cover the water removal and the structural drying that follows.
What Counts as Flood Damage?
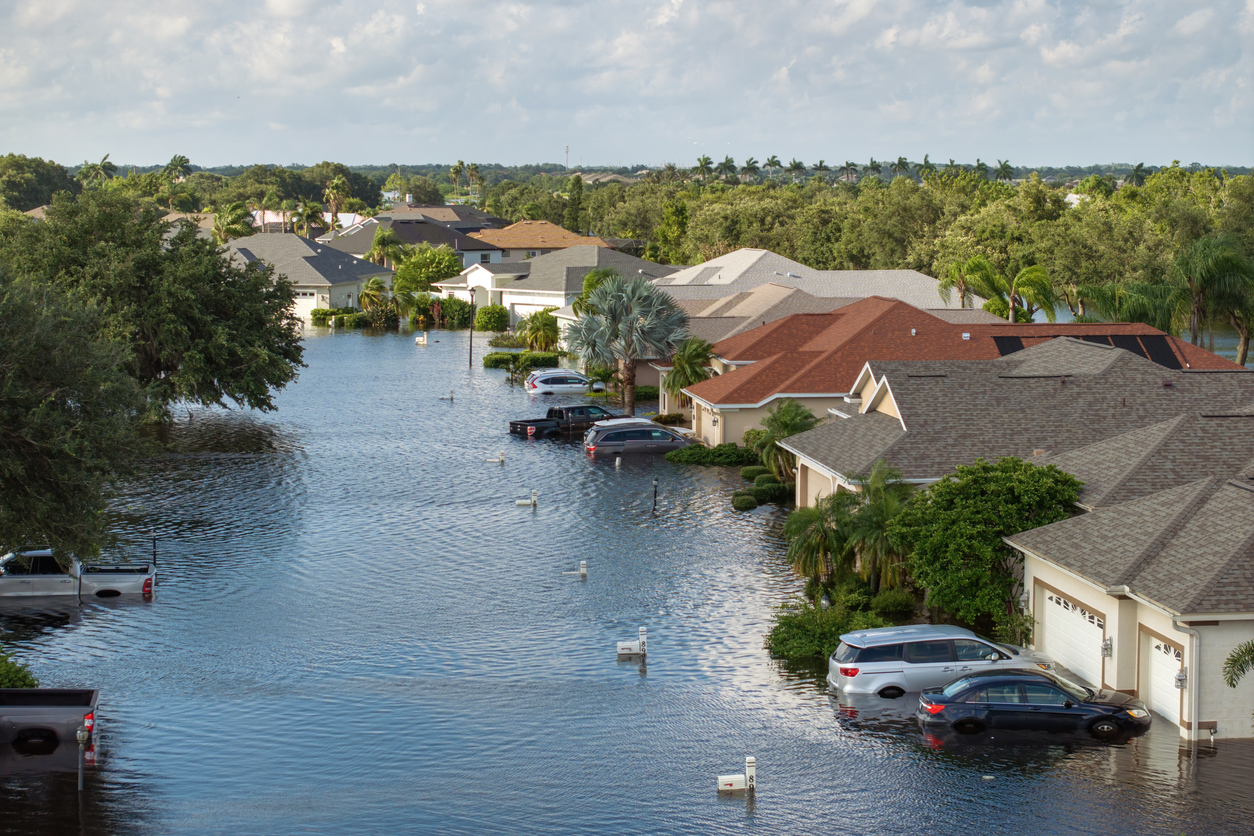
Here’s where many homeowners get blindsided: standard homeowners insurance policies generally do not provide coverage for flood damage under a standard policy. According to FEMA, flood damage is defined as water that originates from an external body of water or saturated ground and rises onto previously dry land.
That includes:
- Rivers, streams, or lakes that overflow their banks
- Accumulated rainfall or runoff that saturates soil and seeps into your home
- Storm surge from hurricanes or coastal storms
- Rapid snowmelt that overwhelms drainage systems
If water rises from the ground up and enters through your foundation, basement, or ground-floor entry points, that’s flood damage. It requires a separate flood insurance policy, either through the National Flood Insurance Program (NFIP) managed by FEMA, or through a private flood insurer. Water backup from sewers is also typically excluded unless you have additional coverage.
Does My Homeowners Policy Cover Any Flooding?
No, and this is one of the most common misconceptions in residential insurance: water damage and flood damage are two different things for insurance purposes, and the main difference is whether the water came from inside the home or from a natural source outside the property. FEMA explicitly notes that standard homeowners’ policies exclude flooding by definition, even when a major storm causes it. For example, damage from a leaky toilet or continuous leaking from neglected pipes is usually not covered because unresolved maintenance issues are not part of your protection. Frozen pipes may also be excluded if you did not take reasonable care to keep the house protected. If your home is in a high-risk flood zone, your mortgage lender may already require a separate flood policy. But homes outside those zones flood too, and the gap in coverage can be financially devastating.
The Gray Zone: When You Have Both Storm and Flood Damage
The toughest claims happen when both types of damage occur at the same time, which is exactly what happens during a major hurricane or tropical storm. You might have:
- Wind that peels back your roof (storm damage: covered)
- Storm surge that floods your ground floor (flood damage: requires a flood policy)
- Rain that enters through the wind-damaged opening (storm damage: covered)
This is called a dual-cause claim, and it’s where things get complicated fast. Many insurers include an “anti-concurrent causation” clause that can limit or deny coverage when an excluded cause like flooding contributes to a loss, even if a covered cause like wind was also involved. In Tennessee, wind or hail claims may also carry separate percentage deductibles that affect what your insurer will pay.
This is a known issue in hurricane-prone states. Courts have ruled on it inconsistently, and some states have passed legislation to limit how insurers apply this clause. If you’re facing a dual-cause dispute after a major storm, document everything before cleanup begins and review any settlement offer carefully to confirm it accounts for all damage and necessary repairs before signing.
ASDT’s catastrophe response team responds after large-scale weather events across Tennessee and can help document the extent of structural damage, information that matters when insurers start drawing lines between covered and excluded causes; homeowners can also use resources from the Tennessee Department of Commerce and Insurance if a claim dispute develops.
How to Strengthen Your Claim After a Storm or Flood
Regardless of the cause, documentation is your strongest tool.
- Photograph and video everything before cleanup begins. Capture the exterior, interior, all water entry points, and damaged contents.
- Note the sequence of events. Did a window break before the water appeared? Was there standing water on the street? The timeline matters to adjusters, and local weather alerts can help document the date and time of the storm.
- Contact your insurance agent or insurance company immediately to start the claim process. Most policies require prompt notification after a loss, and delays can give the carrier grounds to deny it.
- Don’t make permanent repairs before the adjuster visits, but do take reasonable steps to prevent further damage, like tarping a damaged roof, and keep all receipts for temporary repairs.
- If you have to leave the home, save receipts for temporary housing and meals to include with your claim.
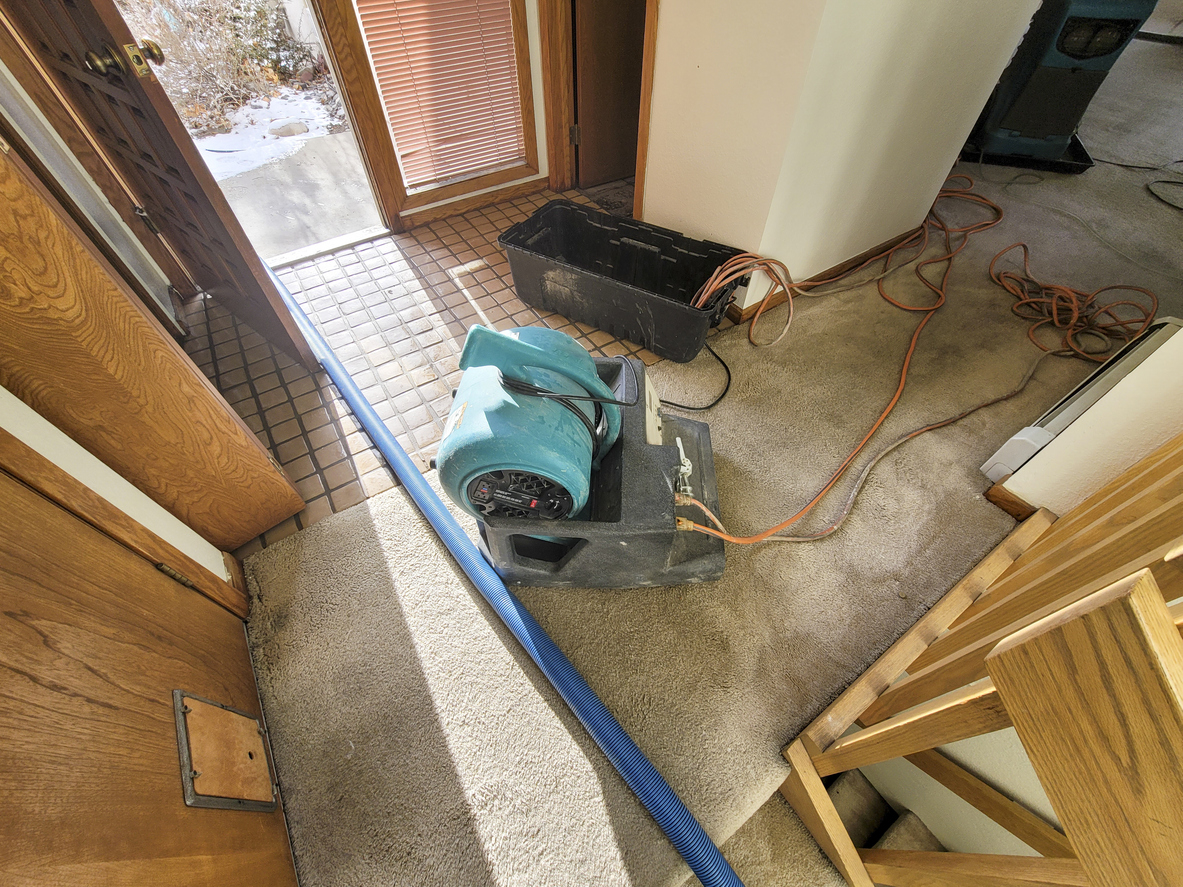
- Start professional mitigation fast. Water compounds quickly. A professional inspection can also help identify hidden or structural damage. Structural drying and dehumidification within the first 24–48 hours dramatically limit secondary damage and mold risk.
- Some policies first pay actual cash value and release recoverable depreciation after repairs are completed.
Frequently Asked Questions
Is wind-driven rain covered by homeowners’ insurance?
Generally, yes, if wind created an opening (a broken window, damaged roof) and rain entered through that opening, the resulting water damage is typically covered as storm damage under a standard homeowners policy.
What is considered flood damage by insurance companies?
Flood damage is water that originates externally and rises onto dry land, including overflowing rivers, storm surge, and surface water runoff. It is excluded from a standard policy because it comes from outside the property, and standard homeowners insurance does not cover flood damage.
Does homeowners’ insurance cover hurricane damage?
Homeowners insurance typically covers wind damage from a hurricane but not storm surge or flooding, which require separate flood coverage. Hurricane claims are often complex because both covered and excluded causes can occur simultaneously. Home insurance may also cover accidental water damage from burst pipes or washing machines, but not storm surge or other flood damage.
Do I need flood insurance if I’m not in a flood zone?
FEMA data shows that roughly 25% of flood insurance claims come from outside high-risk flood zones. Flooding can happen anywhere, so review your homeowners policy or speak with your insurance agent to verify deductible amounts, coverage limits, and whether separate flood coverage is needed if heavy rain is a risk in your area, which can help avoid unpleasant surprises regardless of your official zone designation.
The Bottom Line: Know Your Coverage Before the Storm Hits
Storm damage and flood damage may look the same in your living room, but they are governed by different policies, handled by different adjusters, and they produce very different outcomes. The homeowners who recover fastest are the ones who understood their coverage before disaster struck, documented everything immediately after, and called professional mitigation the same day.
If you’re already dealing with water damage from a storm or flood event, ASDT is available around the clock.
Call ASDT Today For Water Damage Restoration After Storm or Flood Damage in Nashville, TN
Water damage to the property from a burst pipe, a damaged roof, a failed sump pump, or a leaking water heater requires fast, certified mitigation to prevent compounding loss and further property damage. Regular inspections can help keep water lines and appliances working properly and may reduce damage to damaged items after a loss. Contact ASDT or call 615-207-3877 to get a response team on-site today.